

Hello everyone!
If you drive in Alberta, you already know that auto insurance is one of the biggest monthly expenses in our province. The good news is that starting January 1, 2027, Alberta is officially rolling out a brand-new auto insurance system called Care-First Auto Insurance.
I recently dug into the policy details to see how this affects my own renewal, and I wanted to share a clear, practical summary for anyone living and driving in Alberta—especially if you have maintained a clean driving record over the past few years.
Note: I am writing this post solely to share information based on my own reading and understanding of the Government of Alberta’s website: https://www.alberta.ca/care-first-auto-insurance. I am not an insurance broker or agent, so I cannot answer any related questions. Thank you for your understanding.
Table of Contents
1. What is Care-First Auto Insurance?
Previously, Alberta operated under a tort-based insurance model. If you were injured in a collision, getting major compensation often meant hiring lawyers and suing the at-fault driver—a process that drove up legal fees and pushed everyone’s premiums higher every year.
Under Care-First (effective January 1, 2027):
- Immediate Care Regardless of Fault: If you are injured in a crash, you receive medical, rehabilitation, and income replacement benefits directly through your own insurer right away—no matter who caused the accident.
- Fewer Lawsuits: Legal battles over pain and suffering are largely replaced by guaranteed direct care benefits (with exceptions for serious criminal offenses like impaired driving).
- Accountability Remains: At-fault drivers are still held accountable through their driving records and higher insurance premiums.
2. Healthcare is Free in Alberta—Why Does Care-First Highlight Medical Coverage?
At first, I wondered the exact same thing: “We have the Alberta Health Care Insurance Plan (AHCIP), so hospital stays and doctor visits are already covered. Why do we need unlimited medical coverage from our car insurer?”
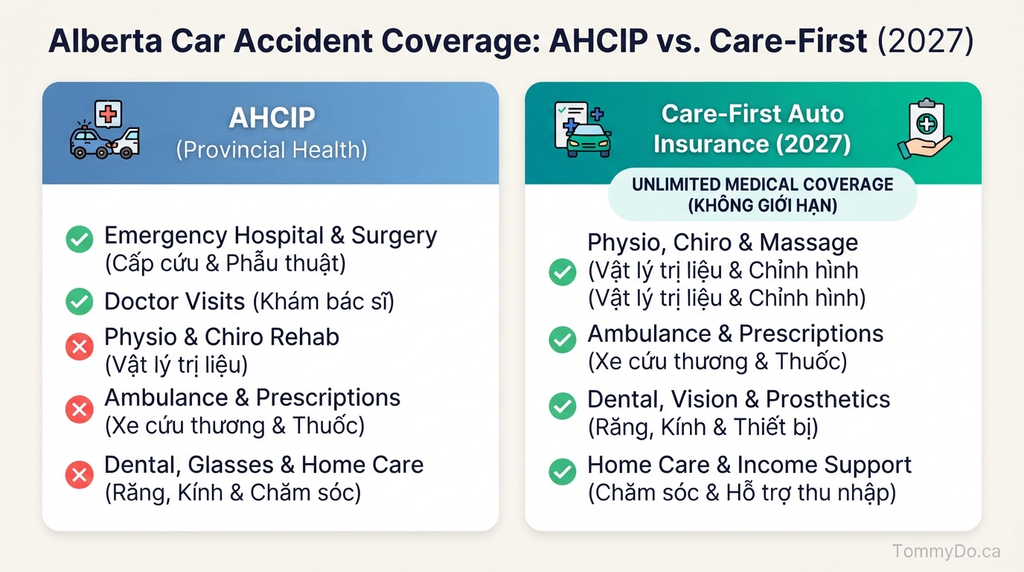
The answer comes down to post-hospital recovery. While AHCIP covers emergency surgeries and physician visits, it does not pay for most long-term rehabilitation services after a collision, including:
- Outpatient Rehab: Physiotherapy, chiropractic care, massage therapy, acupuncture, and psychological counselling.
- Ambulance & Prescriptions: Ground ambulance fees (around $385 in Alberta) and take-home prescription medications.
- Dental & Vision Repair: Restorative dental work or replacement eyeglasses damaged in a crash.
- Catastrophic Support: Prosthetics, mobility equipment, home accessibility modifications, and in-home personal care aides.
Under the old system, your auto insurer capped these benefits at $50,000 for up to two years. Care-First removes that cap, providing unlimited medical and rehabilitation coverage for as long as it is medically necessary for your recovery.
3. Will My Insurance Rate Drop If I Have a Clean Driving Record?
Yes, your rate is very likely to decrease.
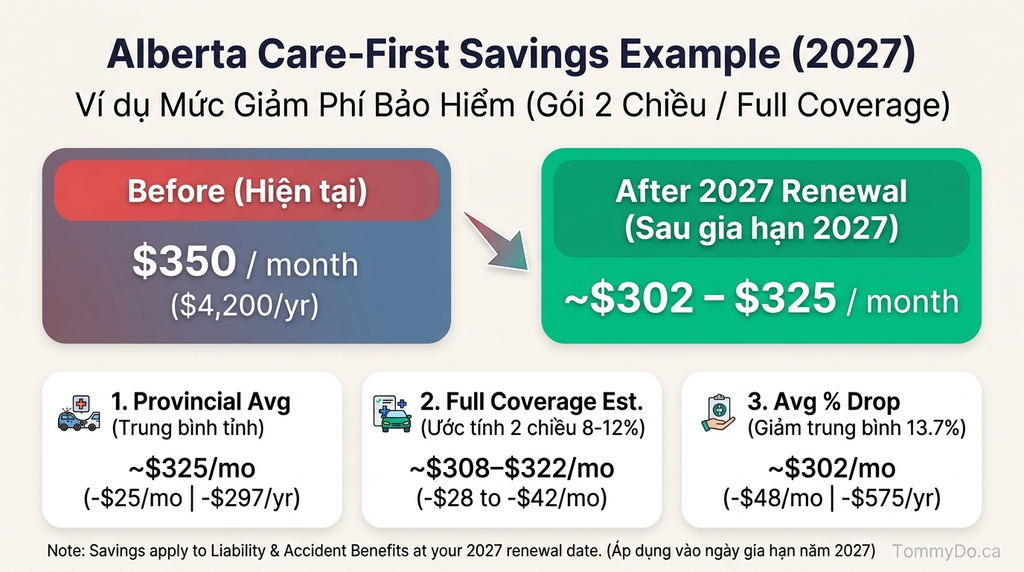
According to filings reviewed by the Automobile Insurance Rate Board (AIRB), roughly 88% to 90% of private passenger vehicles in Alberta are projected to see a price reduction, averaging around $297 per year (or 13.7%).
How much you save depends on your current coverage:
- Basic Liability Coverage: Drivers carrying only mandatory coverage will see the largest percentage drop because Care-First directly reduces Third-Party Liability and Accident Benefits costs.
- Full Coverage (Collision & Comprehensive): Care-First does not lower the cost of physical vehicle damage coverage (like hail, theft, or collision repairs). However, because the liability portion of your policy still drops, someone paying around $350/month for full coverage could still see savings of roughly $25 to $48 per month ($300 to $500+ per year).
Additionally, starting in 2027, the province is enforcing a new 5% average rate increase cap across insurers, and individual renewal increases are capped at 10% (unless your personal risk changes, such as getting a ticket, causing an accident, or buying a more expensive vehicle).
4. When Will My Monthly Bill Actually Go Down?
Keep this timeline in mind so there are no surprises on your bank statement:
- Coverage Starts January 1, 2027: Everyone automatically receives Care-First medical and recovery protections on January 1, 2027.
- Pricing Changes at Your Next Renewal: Your monthly payment will not automatically drop in January unless your policy renews in January. Your rate adjusts on your scheduled 2027 renewal date.
For example, if your policy renews every August, you will keep paying your current rate until August 1, 2027. If you are thinking about cancelling mid-term in January to switch to a new Care-First rate early, check with your provider first—cancelling outside the official fall 2026 transition window may trigger a short-rate cancellation fee.
Final Thoughts
Care-First is a welcome change for Alberta drivers, offering stronger recovery protection while taking some pressure off our monthly budgets. Be sure to review your renewal notice closely when it arrives 45 to 60 days before your 2027 renewal date, and feel free to share this guide with friends and family in Alberta!


